

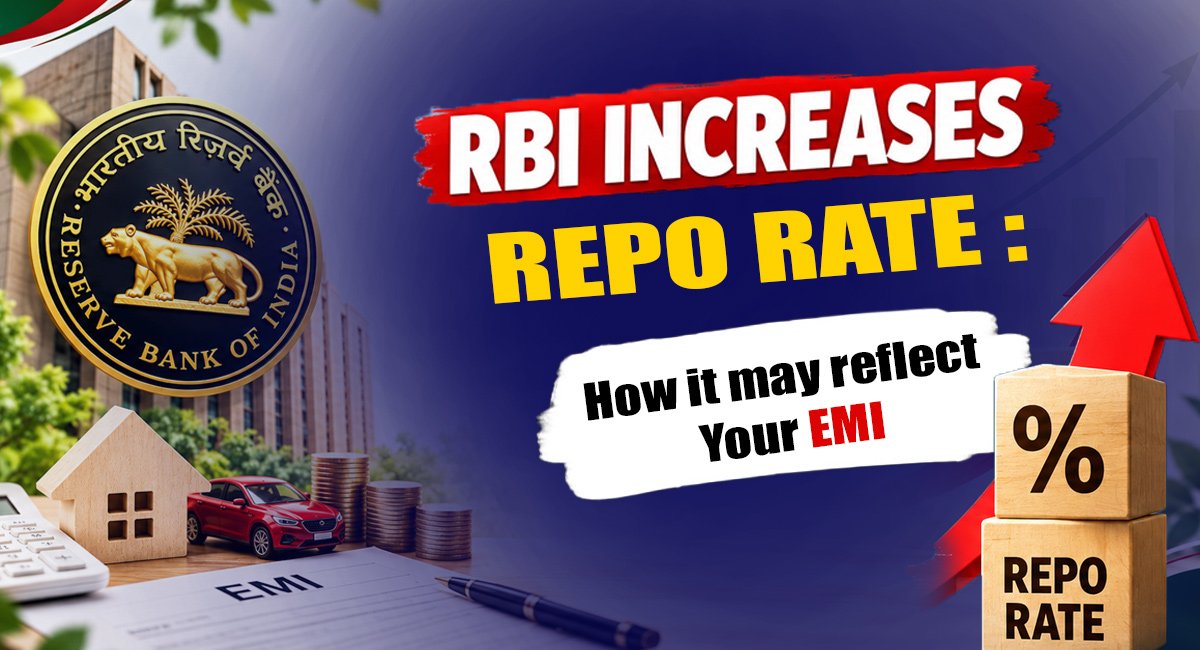
RBI Increases Repo Rate: Your Loan EMI May Go Up
If you have a loan, you may have to pay a little more now.
The Reserve Bank of India, or RBI, has increased the repo rate by 0.25%. This
can affect people who are paying loans with changing interest rates. You may be
thinking, “What does this mean for me? “Let us understand it in very
simple words.
What is the repo rate?
Banks sometimes take money from RBI.The rate at which RBI
gives this money to banks is called the repo rate. When RBI increases this
rate, banks may also increase the interest rate on some loans. And when the
interest rate goes up, your EMI can also go up.
Let us take a simple example.
Suppose you have a home loan and you pay ₹20,000 every month.
Now, if the interest rate on your loan goes up, your monthly EMI may also increase.
So, instead of paying ₹20,000, you may have to pay a little more. The exact
increase will not be the same for everyone. It depends on your loan amount,
interest rate and the time left on your loan.
Which loans can be affected?
This change can affect many loans where the interest rate
can change.
For example:
- Home
loans
- Car
loans
- Personal
loans
- Some
other bank loans
But don't think that everyone's EMI will increase.
It depends on the type of loan you have and the rules of
your bank.
If your loan has a fixed interest rate, you may not see a
change in your EMI right away. The interest rate stays the same for the fixed period.
If you are not sure about your loan, you can simply call your bank and ask
them.
How much can your EMI increase?
There is no fixed amount. It depends on your loan. For
example, someone with a big home loan may see a bigger change than someone with
a small loan. Even if the EMI goes up by a few hundred rupees, it can become a
bigger amount when you keep paying it for many years. That is why it is good to
check your loan once the interest rate changes.
What should you do now?
First, don't panic. Just check your loan details. See how
much EMI you are paying right now. Then ask your bank if the new RBI rate will
affect your EMI. You can also ask them if your loan time will increase. This
will give you a clear idea of what you need to pay.
In some cases, the bank may not increase your monthly EMI.
Instead, it may increase the time of your loan. For example,
if your loan was supposed to finish in 15 years, you may now have to pay it for
a little longer. This can keep your monthly EMI almost the same. But you may
end up paying more interest because the loan will continue for a longer time.
Don't ignore your loan
Many people just pay their EMI every month and don't check
anything else. But it is important to know what is happening with your loan.
Check how much loan is still left. Check your interest rate. And if you hear
about a change in interest rates, ask your bank how it will affect you. It is
better to know early than to get surprised later.
RBI has increased the repo rate by 0.25%, and this may
affect people with loans where the interest rate can change. For some people,
the EMI may increase. For some, the loan may take a little longer to finish. It
will depend on your loan and your bank. So, don't worry too much. Just check
your loan details, talk to your bank and plan your monthly expenses properly.
Knowing these small things can help you manage your money better.
If you already have a loan, it is always better to keep some
extra money in your monthly budget. If your EMI increases, you will be able to
manage it more easily. You can also look at your other monthly expenses and see
if there are small things you can cut down. Even small savings can help.
Discussion & Comments (0)
No comments yet. Be the first to share your thoughts on this story!
Leave a Comment